A practical explanation of issued payments, lender-controlled proceeds, vendor payments, depreciation, and actual funds available for property repairs.
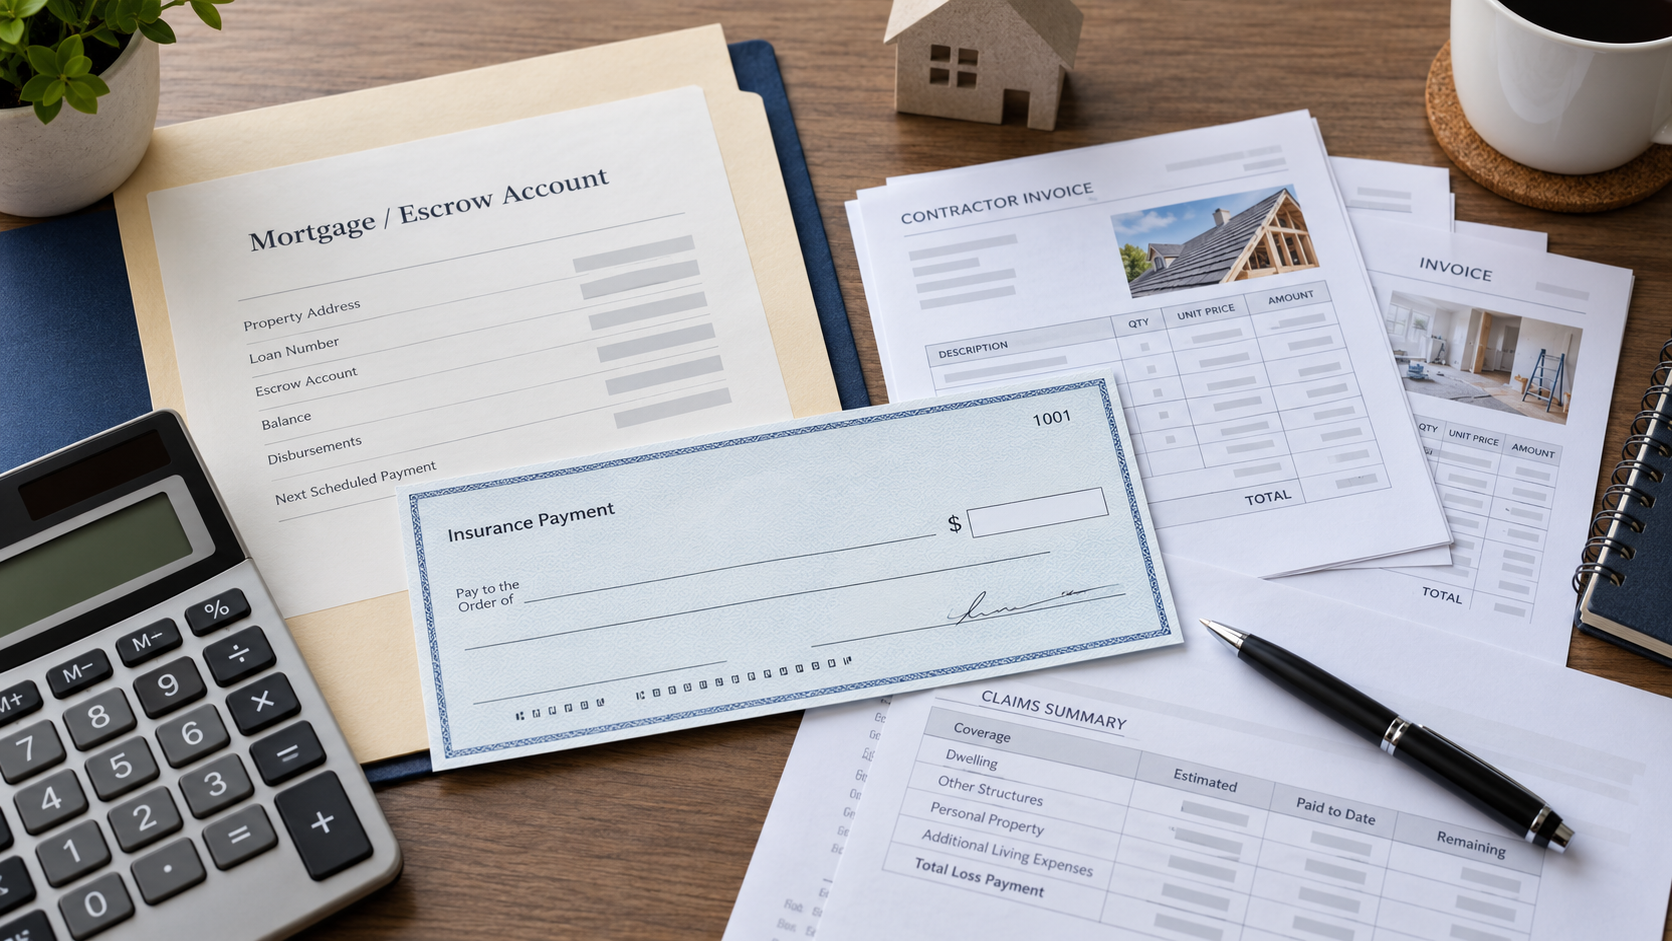
A property owner may receive a letter stating that an insurance payment has been issued, see the amount on a carrier payment ledger, and still be unable to pay the contractor who is ready to begin repairs. That is not necessarily a contradiction. The insurance settlement calculation, the payment instrument, and the owner’s actual access to funds are different parts of the record.
The distinction becomes particularly important in cases of large losses involving mortgage companies, multiple estimates, restoration vendors, replacement-cost conditions, and payments made over several months.
An Estimate Is Not a Bank Balance
An estimate generally provides a valuation of work or property under stated assumptions. It may show replacement cost value (RCV), actual cash value (ACV), depreciation, a deductible, and other coverage-specific calculations. The amounts shown are not necessarily the same as checks issued, checks negotiated, or funds currently available to finance a repair.
The practical question is not only “What did the insurer calculate?” but also “What payment was actually issued, to whom, for what purpose, and what happened next?” A revised estimate can change the valuation record without producing an immediately usable deposit.
Issued, Delivered, Received, and Negotiated Are Four Different Events
A carrier payment log may mark a check as issued when it was prepared or mailed. That notation does not, on its own, prove that it reached the owner. A delivered check may list two or more payees and may not yet have the endorsements required for negotiation. A replacement check may be issued because an earlier instrument was lost, stopped, or returned.
A sound payment history records the instrument date, amount, payees, stated coverage or purpose, and status. Supporting records may include check images, delivery evidence, bank activity, void or stop-payment confirmation, reissue correspondence, and the parties’ descriptions of what occurred.
If the status is unknown, it should remain unknown. A ledger entry marked “paid” should not be changed to “received and available” merely because that change makes the totals easier to reconcile.
Mortgage Companies Can Control Part of the Proceeds
When a property has a mortgage, a dwelling-repair check may be payable jointly to the owner and mortgage lender or servicer. The Consumer Financial Protection Bureau explains that lenders commonly protect their collateral interest and may release funds in stages while repair work progresses. A check made payable to a lender is not necessarily available for direct contractor payment. The owner may need to submit estimates, contracts, endorsements, inspection results, or other documents before funds are released. The applicable mortgage agreement, servicing arrangement, loan status, and lender instructions matter. One servicer’s process should not be treated as a universal rule.
Three figures therefore need separate tracking: the amount sent by the insurer, the amount held or controlled by the lender, and the amount the owner can actually use for eligible work at that point in time. A lender statement can provide a materially different picture from the insurer’s payment summary.
Vendor-Direct Payments Are Not the Same as Owner-Accessible Funds
The insurer may pay a mitigation contractor, restoration vendor, consultant, or other participant directly. Those dollars may properly relate to the claim, but they do not become funds the owner can use to hire a different contractor. Nor should they be automatically counted again as an owner disbursement.
A payment reconciliation should identify the stated purpose of each transfer and whether it applies to the dwelling, personal property, mitigation, additional living expense (ALE), or another category. The recipient and confirmed use matter at least as much as the amount.
Depreciation and Other Conditional Amounts Need Their Own Column
Some replacement-cost policies initially pay an amount reflecting depreciation and permit additional recovery after qualifying repair or replacement activity and documentation, subject to the policy’s terms, limits, deadlines, and conditions. Amounts labeled recoverable depreciation are not necessarily cash already issued or unconditionally available.
Ordinance or law, supplemental scope, paid-when-incurred operations, and other potential amounts may also depend on specific documentation or a later claim determination. These should be distinguished from both disbursed funds and unsupported future expectations.
The policy controls whether and when an additional benefit is payable. A payment ledger does not decide coverage or convert a requested supplement into approved money.
Watch for Reissued Checks and Duplicate Counting
A common accounting problem is the same underlying payment appearing multiple times in the paperwork: once in the carrier summary, once as a check image, once as a voided instrument, and again as a replacement check. Summing all entries can overstate actual disbursements. Another problem arises when a carrier revises an estimate but does not provide a transaction-level explanation showing which prior payments were credited to the revised calculation. The correct response is to trace the instrument chain and estimate versions, not to assume that every unexplained variance is an unpaid benefit.
A Useful Reconciliation Separates Three Records
First is the valuation record: dated estimate versions and the coverage calculations each represents. Second is the transaction record: checks and transfers, payees, categories, amounts, and documented status. Third is the access record: what the owner can use now, what a lender controls, what went to vendors, and what is still conditional or unresolved.
These records can be linked without flattening them into a single total. A homeowner may have an insurer-reported payment amount, a smaller sum negotiated into a lender-controlled account, and a smaller amount released for repairs. All three figures may be correct descriptions of different stages.
Questions Worth Asking Before Work Begins
Request the current estimate, earlier versions of the material, the insurer’s transaction-level payment history, copies of the payment instruments when available, and any lender loss-draft statements or release requirements. Match each entry to its intended coverage and recipient. Identify missing check statuses, unverified deliveries, unresolved vendor payments, and the dates or conditions governing remaining benefits.
Keep structure, contents, ALE, ordinance or law, and other coverage categories separate unless the actual policy or accounting purpose justifies combining them. A clear record helps the parties determine whether a problem concerns valuation, payment issuance, endorsement, lender release, or a disputed coverage condition.
The Bottom Line
“The insurer issued the money” doesn’t settle the financial question. A defensible claim reconciliation shows what was valued, what was sent and received, where the funds are held, what has been spent, and what remains conditional or unexplained. This distinction helps owners, contractors, and claim professionals discuss repair financing without mistaking payment history for cash that is actually available.
Sources and further reading
Consumer Financial Protection Bureau, How Do Home Insurance Companies Pay Out Claims?: https://www.consumerfinance.gov/ask-cfpb/how-do-home-insurance-companies-pay-out-claims-en-1523/
Fannie Mae, Servicing Guide B-5-01: Insured Loss Events: https://servicing-guide.fanniemae.com/svc/b-5-01/insured-loss-events
NAIC, Actual Cash Value vs. Replacement Cost: https://content.naic.org/article/whats-difference-between-actual-cash-value-coverage-and-replacement-cost-coverage
Absolute Adjusting, Claim Financial Reconciliation: https://absoluteadjusting.com/claim-financial-reconciliation/
General education only, not legal advice or a coverage determination. Individual policy language, records, engagement scope and applicable law control.