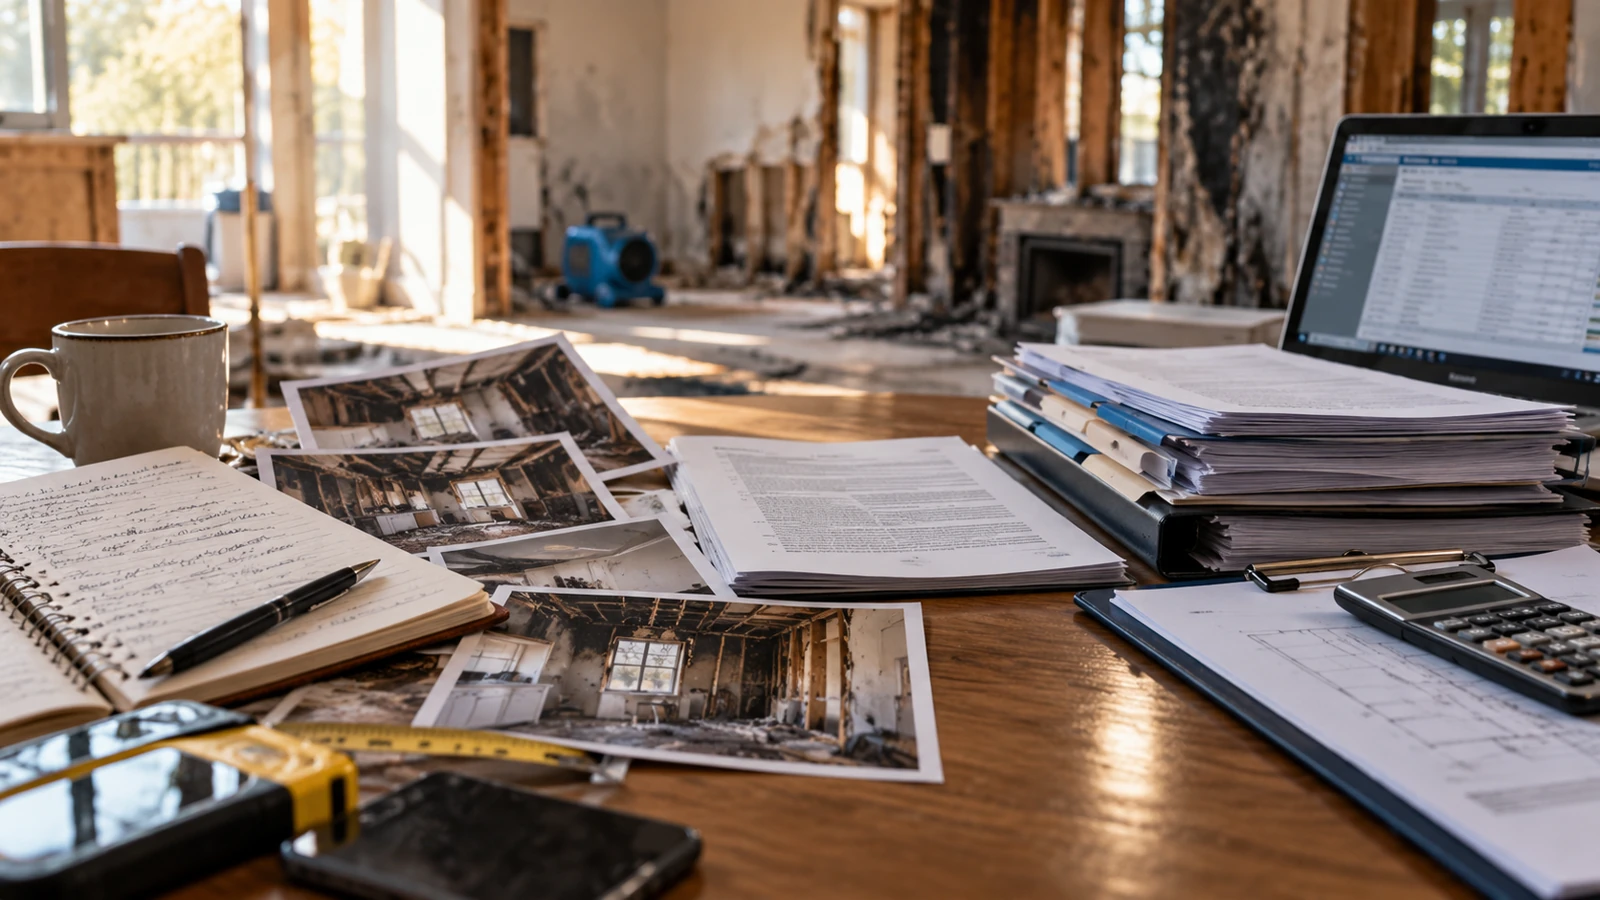
A major property loss can turn an owner into the manager of an unfamiliar project overnight. There may be damaged rooms, displaced occupants, interrupted operations, and decisions about protecting what remains. At the same time, the insurance claim requires photographs, measurements, inventories, estimates, and timely responses.
The insurance company already has a claims operation. It has people, procedures, estimating systems, and access to specialists. A property owner may be encountering this work for the first time while trying to keep a household, business, or community functioning.
The insurer has experienced professionals handling its side of the claim. On a significant loss, who is handling yours?
That difference in experience can matter even when everyone involved intends to handle the claim properly. A public adjuster may help the policyholder understand the work, build the supporting record, and present a documented claim. The question is whether the particular loss requires that level of assistance.
Fair claim handling and policyholder representation are separate responsibilities
An insurer's obligation to handle claims fairly does not depend on whether the policyholder hires someone. The insurer must fulfill its responsibilities under the policy and applicable law. For example, Arizona's claims-handling statute addresses reasonable investigation and communications as part of defined unfair-claims standards. The rule is not a determination about any particular insurer or loss. Those standards do not make the insurer's adjuster the policyholder's separately retained representative. [Arizona statute]
A staff adjuster works for the insurer. An independent adjuster may be a contractor rather than an employee, but when retained by the insurer, that adjuster carries out the insurer's assignment. A public adjuster is retained on the policyholder's side to assist with claim preparation, presentation, and negotiation within the authorized scope. Arizona's insurance regulator explains this distinction. [Arizona DIFI]
Hiring a public adjuster does not establish that the insurer has acted improperly. It also does not create coverage, remove policy conditions, or guarantee a different settlement. It gives the policyholder professional assistance with the claim work that must be done.
Where the experience gap becomes practical
The following are illustrative situations, not descriptions of private client files.
Recognizing what is missing from the repair scope
- An estimate may include replacement drywall but leave unanswered how attached finishes will be removed, protected, or restored. A property owner may notice that the total seems low without knowing which activities account for the difference.
- A useful review asks what the repair actually requires and where each necessary activity appears in the estimate. It also checks whether work is included elsewhere before calling it an omission. Photographs, measurements, and qualified technical recommendations provide a stronger basis for discussion than simply asking for more money.
Understanding why estimates differ
- Two estimates may disagree because they describe different work, use different quantities, apply different prices, or assume different repair methods. Increasing a unit price cannot correct an omitted room. Correcting a measurement cannot resolve a disagreement about whether a component can be repaired.
- An experienced claim professional separates these questions and identifies the support needed for each. The Claim Library's guide to scope, quantity, price, and methodology explains these distinctions in greater detail.
Turning a contents list into supporting documentation
- After a fire, an owner may recall the kitchen contents but overlook storage areas, seasonal items, or equipment kept in multiple locations. Photographs can also show the same object more than once.
- Effective inventory work links descriptions, quantities, and replacement research to available evidence. Uncertain identifications remain visible for review. The goal is to document what was actually present, without omissions, duplication, or unsupported upgrades. Why Large Contents Inventories Break Down addresses the controls behind that process.
Testing a proposed repair method
- One document may recommend cleaning a damaged material, while another recommends removal. The owner needs to understand the basis for each position, not merely which estimate has the higher total.
- The claim review should identify the technical question and the appropriate evidence. Depending on the issue, that may require input from an engineer, hygienist, manufacturer, code official, or other qualified professional. A public adjuster should not substitute an unsupported opinion for expertise outside the scope of the assignment or qualifications.
Separating value from payment conditions
- Replacement cost, actual cash value, and depreciation describe different aspects of a claim. A payment below the replacement estimate does not, by itself, indicate whether the difference is depreciation, a deductible, a limit, excluded work, or another adjustment.
- The National Association of Insurance Commissioners distinguishes replacement-cost coverage from actual-cash-value coverage, which accounts for depreciation. The applicable policy still governs the particular claim. A useful review separates those calculations and identifies any conditions or documentation required for additional payment, rather than assuming every withheld amount is automatically recoverable. [NAIC consumer guidance]
Keeping deadlines and settlement records visible
- An owner may be actively repairing a property while missing a separate request for information. Notices, proof-of-loss, replacement-cost, and legal-action deadlines may differ. Their application can depend on the policy, state law, and written extensions.
- A dated record should document what was requested, what was supplied, the applicable due date, and what remains unresolved. Do not assume that ongoing discussions extend a deadline. Questions about legal rights or filing deadlines should be referred to qualified counsel.
- Payment records also need organization. A revised estimate, an advance, a payment to multiple payees, and a proposed settlement document may address different matters. The owner should understand which portions are resolved and which remain open. Legal advice may be needed before signing a release or other document affecting rights.
When professional representation may be valuable
The strongest reason to consider a public adjuster is a defined need, not simply dissatisfaction with the first estimate. Useful indicators include:
- Several components of the loss must be coordinated, including building damage, contents, and loss-of-use documentation.
- Significant scope or valuation differences cannot be explained by the available record.
- The inventory or supporting documentation is extensive and difficult to organize.
- The owner lacks the time or experience to manage repeated submissions, comparisons, and unresolved requests.
- A property manager or association board needs a clear record of the claim's status, supporting documents, and outstanding decisions.
For a management company or homeowners association, experience operating property does not automatically translate to experience adjusting a substantial insurance loss. Authority also matters: identify the insured entity, the person authorized to retain assistance, and the responsibilities of owners, managers, and boards. Legal questions about governing documents or competing insurance obligations belong with counsel.
The appropriate engagement should define the work to be performed, the records needed, and its limits. Representation should produce a clearer claim record, not just a larger stack of correspondence.
When a claim may not justify full representation
A straightforward, adequately documented loss may be manageable directly with the insurer. If the scope is understood, the questions receive clear answers, and no material dispute remains, full representation may add little practical value.
Consumer guidance from Colorado regulators recognizes that hiring a public adjuster is optional and that a policyholder may obtain a fair settlement directly from the insurer. An owner should ask questions, seek an itemized explanation, and review any proposed public-adjusting agreement before deciding to hire help. [Colorado Attorney General advisory]
For a smaller or narrowly defined issue, a separate consultation may be more appropriate than full public-adjusting representation. That could involve identifying the unresolved question or reviewing an estimate comparison, subject to a defined assignment and suitability review. It should not be assumed to include ongoing negotiation or management of the entire claim.
Before retaining anyone, consider the actual work needed, the cost and terms of the proposed engagement, the professional's relevant experience, and who will perform the work. Verify licensing where required. Legal disputes may require an attorney rather than, or in addition to, a public adjuster. Our guide to public adjusters and attorneys explains the different roles.
Claim assistance is not contractor selection
Absolute Adjusting does not direct, select, or recommend contractors. Our focus is on the insurance-claim process and the policyholder's documented claim.
Reviewing a repair estimate or documenting a repair-method disagreement does not make us the construction manager. Contractor selection, contracting, and construction performance remain separate responsibilities. The scope of any professional assignment should make those boundaries clear.
A useful relationship can begin before a loss
Property owners, management companies and association boards can benefit from knowing whom to contact before an unfamiliar claim becomes urgent. Current policy records, property photographs, inventories and clear decision-making authority can make later claim work easier to organize. An introductory conversation does not establish standing representation or an obligation to accept a future assignment.
Absolute Adjusting provides public adjusting and claim-related assistance for eligible property owners and associations, subject to licensing, conflicts and a defined engagement. To discuss whether a matter warrants full representation or a narrower consultation, use our initial-review contact path. Please do not send confidential claim documents through the website inquiry form.
This article provides general educational information only. Coverage, duties, deadlines and available services depend on the policy, applicable law and the facts of the assignment. This article does not provide legal advice, create a professional relationship or promise any claim outcome.