Your dwelling coverage limit and the cost to reconstruct your home are not necessarily the same number.
Most homeowners know what they paid for their house, the mortgage balance, and roughly what the property might sell for today. Far fewer know what it would cost to rebuild the dwelling after a major fire, windstorm, or other covered loss.
That difference matters. A policy may renew for years with adjustments to the dwelling limit, but an automatic increase doesn't necessarily mean the amount reflects the home as it exists today. The practical question is simple: if the building had to be rebuilt, would the available coverage reasonably match the work required?
Replacement cost is not the home's market value
The price a buyer pays for a home reflects land, location, market demand, and other real-estate conditions. A dwelling reconstruction estimate covers the cost of rebuilding the structure with appropriate materials, labor, and methods. These two measures can move in different directions.
Neither the tax assessment, the real-estate listing, nor the outstanding mortgage balance reliably substitutes for a current reconstruction-cost estimate. The National Association of Insurance Commissioners explains that dwelling coverage should be evaluated against the cost to rebuild, not the property's sale value.
What actually drives the cost to rebuild?
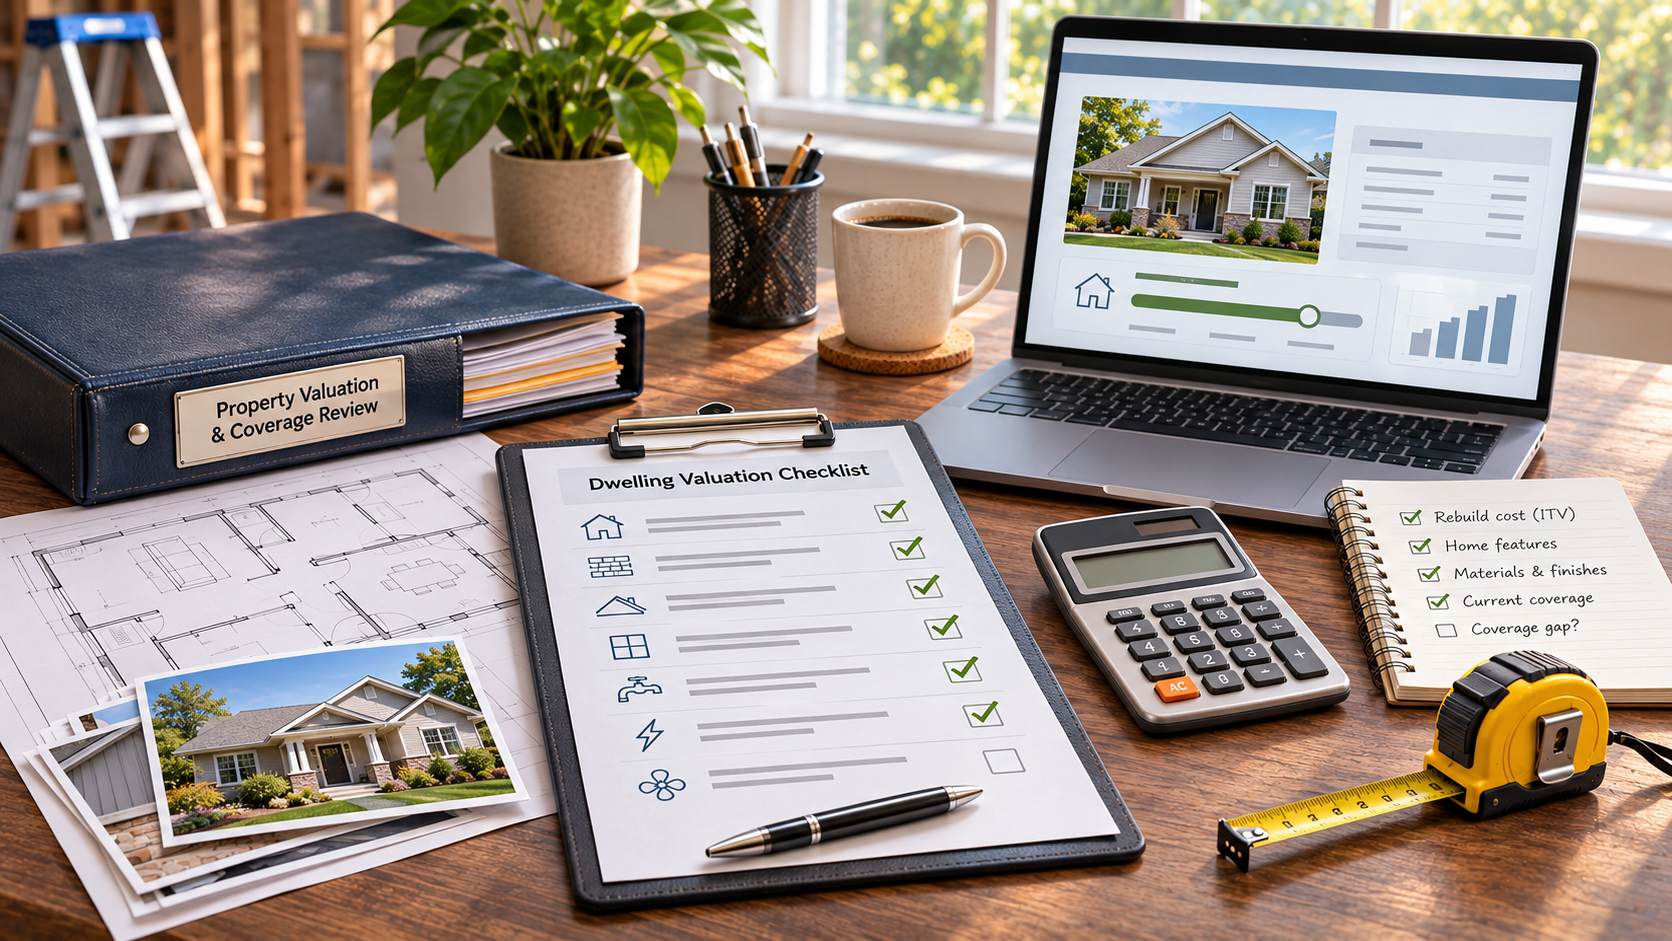
A meaningful insurance-to-value (ITV) review starts with the building, not a price-per-square-foot guess. The reviewer needs to understand the dwelling's age, finished living area, number of stories, construction quality, style, and any unusual access or site conditions.
The details matter. Foundation type and slope, roof shape and material, exterior wall construction, windows, ceiling heights, interior wall and floor finishes, kitchens, bathrooms, heating and cooling systems, fireplaces, attached garages, decks, and additions can materially affect the estimated work. Two houses with similar square footage may have very different reconstruction requirements.
The estimate may also need to address demolition and debris removal, contractor overhead and profit, local labor and material costs, fees, and work required by applicable building codes. These components depend on the valuation scope, property characteristics, location, and the methods used. A figure isn't complete just because it looks precise.
The 80% rule is not a rebuilding budget
Some homeowners have heard they need to insure a dwelling for only 80% of its replacement cost. Many policies use an insurance-to-value provision based on that percentage, particularly when determining how replacement-cost settlement provisions apply to certain losses. The actual effect varies by policy.
But 80% is not the same as having enough money for total reconstruction. If it would cost $500,000 to rebuild a home and the dwelling limit is $400,000, the apparent difference is $100,000 before considering the deductible, applicable endorsements, or other limitations. Meeting a percentage threshold does not make that difference disappear.
The sensible starting point is the estimated full reconstruction cost, followed by an examination of what the policy actually provides. A licensed insurance agent can explain the available limit, the form, and how its replacement-cost conditions operate.
Extended replacement cost and building-code coverage need their own review
Extended and guaranteed replacement-cost provisions are not interchangeable. An extended replacement-cost endorsement may provide an additional amount above the stated dwelling limit, subject to specific percentages, conditions, and exclusions. A guaranteed replacement-cost provision may operate differently. Neither description should be accepted without reviewing the applicable wording.
Ordinance or Law coverage warrants separate attention. Rebuilding an older dwelling may require work to comply with current codes that was not part of the original construction. Whether the policy pays for that additional expense, in what amount, and under what conditions depends on the specific form and endorsements. An increase in the dwelling limit alone does not establish that every code-related cost is covered.
Do not overlook the rest of the property
The house is only one part of a homeowner's insurance exposure. Furniture, clothing, tools, electronics, appliances, collections, and property stored in closets, garages, cabinets, and storage areas can represent substantial replacement costs. A personal-property limit calculated as a percentage of the dwelling limit may not reflect what the household actually owns.
Additional Living Expense coverage also matters. Temporary housing and other eligible increased living costs can become significant during a lengthy reconstruction, while the policy may impose limits, conditions, and time restrictions. Other structures, such as detached garages, sheds, workshops, barns, or fences, may require their own limit review. Rural properties often call for particular attention to outbuildings and unusual improvements.
Restrictions concerning flood, sewer or drain backup, roofs, depreciation, special categories of property, and other perils can also change the protection available. No single ITV figure answers all of these policy questions.
Five questions worth asking before the next renewal
- When was the dwelling reconstruction value last developed based on the home's actual features, rather than merely increased by a renewal factor?
- Does the valuation accurately describe the present building, including finished basement space, additions, exterior materials, specialty systems, garages, and the quality of its finishes?
- Does the figure reflect local rebuilding conditions and any important assumptions or exclusions, including how demolition, permits, code work, or detached structures are treated?
- Which additional replacement-cost and Ordinance or Law provisions apply, and what would they require following a loss?
- Are personal property, other structures, temporary living expenses, and special limits appropriate for the property and household?
The answers should be discussed with the insurer or a licensed insurance agent. The point is to understand the assumptions and options before a loss, rather than to discover material gaps during reconstruction.
How an independent dwelling replacement-cost review can help
An independent reconstruction-cost review offers another assessment of the dwelling's physical characteristics and the estimated cost to rebuild at the time of the review. It may identify incorrectly classified construction, omitted features, questionable quantities, unusual site conditions, or assumptions that warrant further investigation. Absolute Adjusting's optional Independent Dwelling Replacement-Cost Review is intended to provide the homeowner with a documented assessment for discussion with a licensed insurance agent. The review is a separate professional service. It does not sell or bind insurance, select the coverage limit for the owner, establish what an insurer must pay, or guarantee that the property is adequately insured.
A homeowner can make this discussion more productive by maintaining a current record of the home: photographs, approximate dimensions, major renovations, construction features, and information on attached or detached improvements. Those records remain useful whether or not the owner seeks professional assistance.
Review the number before you need it
Don't choose a dwelling limit based on premium alone. Review the rebuilding assumptions when you buy or renew a policy, after significant renovations or additions, and whenever local construction costs or the property's condition change. Ask for a written explanation of the dwelling amount and what it includes and excludes.
Discovering that the estimate may be incomplete is far easier to address while the house is standing than after a major loss. If you would like a separate reconstruction-cost assessment, contact Absolute Adjusting to discuss whether an Independent Dwelling Replacement-Cost Review is appropriate for your property. Any professional work requires its own scope and terms. Maintaining your own property records does not obligate you to purchase services or consent to the sharing of those records.
Sources and further reading
NAIC Consumer Home Insurance Guide | NAIC Replacement Cost vs. ACV (2025) | Insurance Information Institute: Disaster Coverage
General education only. Coverage depends on the actual policy, endorsements and circumstances. An ITV estimate is not a guarantee of rebuilding price or adequate limits.