New disclosure rules give Colorado property owners a clearer view of wildfire classifications and documented mitigation. The score still needs context.
The immediate answer
Colorado homeowners whose insurers use wildfire risk models now have a more specific way to ask why their property received a particular classification and whether mitigation work was recognized. Under HB25-1182, new disclosure requirements took effect in October 2026. A useful step is not to assume a favorable score or a guaranteed discount. Instead, request the actual notice, examine what it says, and preserve evidence of the work done at the property. The Colorado General Assembly lists the act as effective July 1, 2026. The Colorado Division of Insurance (DOI) states that the related consumer notice requirements took effect October 1, 2026. These are different milestones, not conflicting dates. The DOI describes the provisions as applying to admitted insurers and the Colorado FAIR Plan, but not to non-admitted or surplus-lines insurers. The rules focus on risk assessment, rating, and underwriting rather than the adjustment of a particular fire claim.
What should the notice actually tell you?
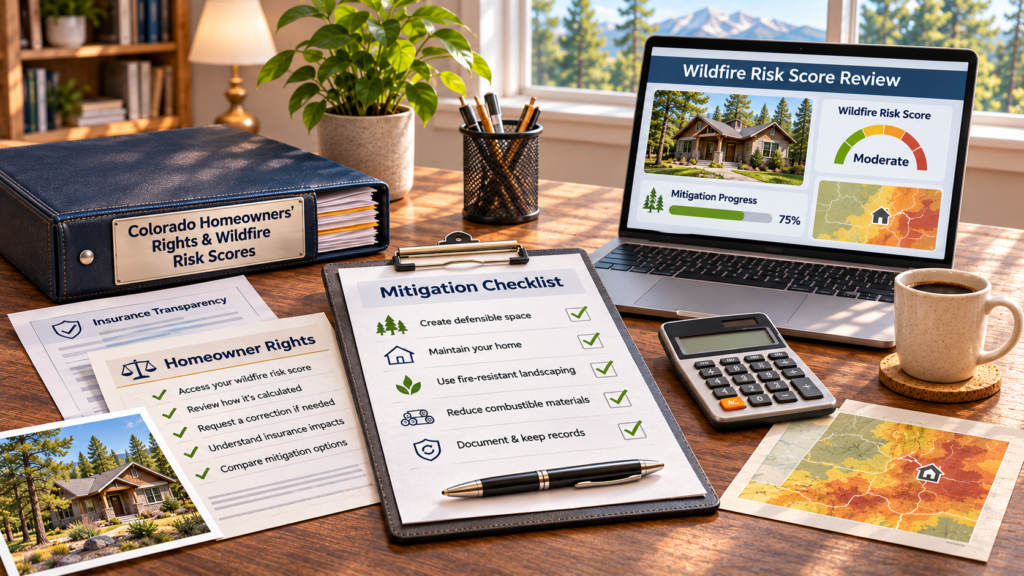
The DOI explains that when an insurer uses wildfire models or scores to underwrite, price, surcharge, or nonrenew a policy, its written notice should identify the property’s wildfire risk score or classification, explain the methodology in plain language, show the range of possible scores, and describe the property or surrounding-area characteristics that affected the result. The notice should also explain how mitigation affects the result and describe the appeal process. For a newly completed application, the DOI specifies that the score and explanation should be delivered within 15 days. Existing insureds should look for this information with their renewal offer or nonrenewal notice. If a homeowner receives only a number without a meaningful description, they should ask the insurer or agent which factors produced the result and where to obtain a fuller explanation. An adverse risk classification does not, by itself, show that the insurer made a mistake. Location, access, vegetation, fire protection, construction features, and the insurer’s actual underwriting criteria may all matter. The key question is whether the information is clear enough to check.
Mitigation is useful only if it is documented and recognized
The legislation covers both property-specific and community-level mitigation. Examples include defensible-space work, building-hardening measures, and eligible community fuel reduction. The applicable practices and verification methods depend on the insurer’s published standards. The DOI references recognized scientific designations, including those associated with the Insurance Institute for Business & Home Safety (IBHS). Preserve dated before-and-after photographs, receipts, contractor descriptions, inspection reports, certification records, and communications with an association or local fire-mitigation program. If you completed the work yourself, a dated description and supporting photographs may help, though the insurer may require an additional inspection or certification. Mitigation does not guarantee a lower premium or a particular underwriting decision. Homeowners can reasonably request an explanation of which activities qualify, whether the work was considered, and what steps are needed for reconsideration.
How the appeal and timing process works
According to the DOI, an applicant or policyholder can appeal an inaccurate wildfire risk score, classification, or mitigation discount. A formal appeal should identify the specific disputed factor and provide evidence, rather than simply asserting that the premium is excessive. The DOI’s October 12 guidance outlines acknowledgment within 10 calendar days and a written reconsideration decision within 30 calendar days. It also addresses continued coverage in certain circumstances when an appeal extends past expiration. The actual policy and operative rules should be reviewed for those conditions. Keep a complete copy of the notice and appeal, the evidence submitted, the delivery date, any acknowledgment, and the written response. A homeowner should not assume that submitting an appeal automatically binds renewal coverage or eliminates an upcoming payment obligation.
Five practical questions for your agent or insurer
- What wildfire risk score or classification is assigned to this property, and how does it compare with the insurer’s full scale?
- What specific property features, location factors, and community conditions affected that score?
- Which mitigation measures are recognized, and what evidence or certification is required?
- Does the insurer offer a discount, incentive, or adjustment for those measures, and what conditions apply?
- What is the written procedure for seeking reconsideration, and when should a response be expected?
For rural properties, don’t overlook outbuildings, attached improvements, difficult access, or changes since the most recent inspection. The score may not accurately reflect the dwelling if the insurer relies on outdated records. Confirm the property description and the numerical classification.
What this changes, and what it does not
A risk-score notice is not an estimate of reconstruction costs, a promise to renew, or an explanation of coverage after a loss. Homeowners still need to review the dwelling limit, contents coverage, policy endorsements, deductibles, and exclusions. A separate reconstruction-cost review may raise questions that a wildfire score cannot answer. The new framework’s practical benefit is greater transparency. Homeowners can ask more specific questions, submit evidence of mitigation, and keep a written record of the insurer’s response. Licensed insurance agents and insurers are responsible for coverage selection, policy placement, and premium recommendations. Claim-adjustment assistance is a separate professional service. If the insurer does not provide the required information or address submitted mitigation evidence, the DOI lists its Consumer Services Team at 303-894-7490 and DORA_Insurance@state.co.us as a resource. Keep the notice and correspondence before requesting assistance.
Sources and further reading
- Colorado General Assembly, HB25-1182, Risk Model Use in Property Insurance Policies (enacted; effective July 1, 2026)
- Colorado Division of Insurance, New Homeowners Insurance Protections and Transparency Rights (October 12, 2026)
- Colorado DOI, official agency site
Explore more property-insurance guidance in the Claim Library.