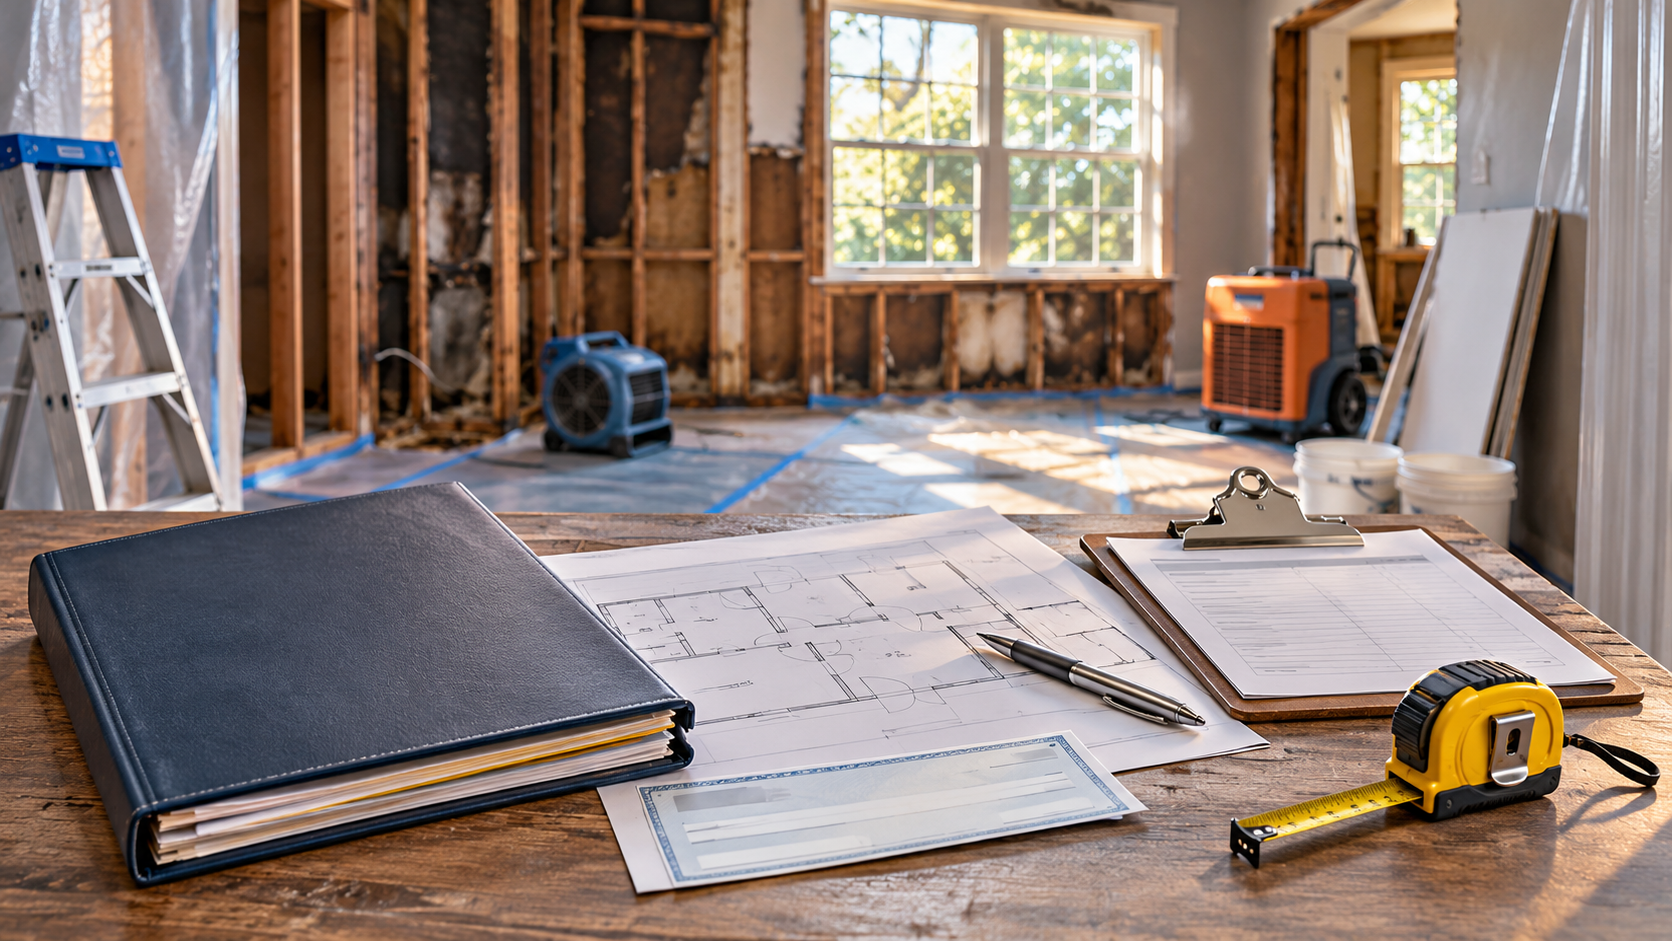
An issued check, an available construction budget, and a repair-ready scope are three different things.
An insurer may report that a property claim has been paid while the home still has exposed framing, damaged finishes, or unusable rooms. The contractor may not have started, or the work may have stopped. To the owner, the situation seems contradictory: if the claim was paid, why is the property not repaired? The answer isn’t always a disagreement over the settlement amount. Insurance payments, access to those funds, the repair scope, contractor readiness, and the order of necessary work are separate steps. A delay can arise at any one of them, and sometimes at several at once. Before assuming that the insurer, contractor, lender, or property owner is responsible, identify the precise obstacle: What payment, decision, document, inspection, or authorization is required before the next repair operation can occur?
Industry repairs may be getting faster, but not every loss follows the average
J.D. Power reported in its March 2026 U.S. Property Claims Satisfaction Study that the average time required to complete a repair was 29.6 days, while the average time to final payment was 40.7 days. The study also reported shorter repair cycles among higher-severity claimants who used insurer-connected direct repair programs. Those findings deserve attention: a managed repair arrangement can provide useful coordination and contractor access. At the same time, October 2026 restoration-industry reporting described shortages of construction and adjusting labor, operating-cost pressures, and challenges meeting customer expectations. The reporting relied substantially on representatives of Crawford & Company, which operates a managed repair network. Its observations provide useful industry context, not an independent assessment of every program or contractor. Neither national averages nor industry commentary establish how long a major fire, water, or catastrophe restoration should take. Complex work may require specialized contractors, testing, engineering, permits, and lender draw approvals that ordinary repair-cycle statistics do not explain.
First question: Was the payment issued, received, or actually available?
An insurance company can issue a building-damage check without the entire amount becoming immediately available for reconstruction. The instrument may name a mortgage lender as a payee, require endorsement, or be deposited into a lender-controlled loss-draft account. The lender may impose documented disbursement conditions before releasing construction funds. Other claim payments may go directly to a mitigation company or temporary-housing provider. The settlement figures also serve different purposes. Replacement cost value, actual cash value, the deductible, amounts previously paid, recoverable depreciation, and costs payable when incurred should not be treated as a single available balance. The operative policy and payment documentation determine how to treat each category. The National Association of Insurance Commissioners explains that homeowners claims commonly involve multiple payments for separate parts of a loss, not one transaction that finishes the entire claim. A useful accounting therefore asks what was issued, who the payees were, whether it was delivered and negotiated, what the lender controls, and what the owner can actually use. A payment letter alone cannot answer all of those questions. Conversely, a lender hold does not prove the insurer failed to issue payment.
Second question: Does the approved estimate describe work that can actually be completed?
An insurer estimate identifies the work and pricing included in that particular assessment. It is not automatically a construction contract, a final engineering design, or a commitment that a contractor can perform every necessary operation for its total. A contractor proposal may also contain allowances, exclusions, or conditions that require clarification. Start by comparing work, not just totals. Does the scope include access and protection, required removal, disposal, drying or cleaning, replacement materials, labor, equipment, detach-and-reset operations, and the steps needed to put the property back together? Are quantities and units supported? Has any specialized work been clearly assigned? Sequence matters. General reconstruction may have to wait for controlled demolition, environmental work, engineering, inspections, or permitting. An estimate that prices one operation without its necessary follow-on work can appear financially complete while remaining operationally incomplete. Conversely, a contractor may propose betterments or elective work that the insurer has not accepted. A higher bid by itself does not establish an insurance underpayment. The productive comparison identifies each specific difference, the supporting photographs or reports, the proposed method, and the party responsible for resolving it. Code-related work requires identification of the applicable requirement and its relevance to the actual repair; payment for that work is a separate policy question.
Third question: Is a contractor ready and authorized to proceed?
Even when funding and scope are adequately documented, a project may be delayed by contractor availability, specialty trade scheduling, supply lead times, permits, safety controls, or the owner’s construction decisions. An estimate does not reserve a crew, and an unsigned proposal does not establish a start date. Managed repair programs may help connect owners with participating contractors and streamline communication. The J.D. Power study found a meaningful time advantage in higher-severity claims using direct repair programs. That result should not be dismissed. But participation still calls for practical questions: Who is contracting for the work? What is included and excluded? Who addresses concealed damage and supplements? What workmanship or warranty commitments apply? How will scheduling changes be communicated? Whether an owner may or must use a particular repair arrangement depends on the operative policy, applicable law, and the circumstances. Do not assume the answer from a carrier referral or a general industry statement. Construction contract advice belongs with qualified construction and legal professionals where appropriate.
Fourth question: What keeps running while repairs are on hold?
Time-sensitive obligations do not necessarily pause while a building remains unfinished. Temporary housing may have a lease end date and an earlier notice requirement. A vendor may have been authorized through a stated date without proof that every related invoice has been paid. The owner may need to preserve damaged materials, protect the property safely, or respond to an inspection or permit requirement. Additional Living Expense, replacement-cost recovery, code-related benefits, and other timing questions depend on the applicable policy and facts. Keep the approved coverage period, actual paid-through date, lease obligations, and any policy or contractual deadline separate. An estimate revision or an unanswered email should not be assumed to extend a deadline. A simple dated record of decisions, requests, responses, and work dependencies is more useful than repeatedly asking every participant for a general update. Follow up when a defined commitment becomes due, when a material fact changes, or when a genuine deadline requires action.
A practical repair-readiness check
When work is not moving, the owner and claim professionals can focus on six specific questions:
- What building work has the insurer accepted, what remains disputed, and which estimate version is current?
- What amounts have been issued, received, paid directly to vendors, held by the lender, or made accessible to the owner?
- What exact operations, quantities, methods, or conditions are missing from the proposed repair scope, if any?
- Which inspection, test, permit, environmental step, or other predecessor task must occur before the next trade can begin?
- Which contractor has proposed an executable scope and schedule, and what funding or authorization does that proposal require?
- Which dates affect housing, property protection, claims documentation, or contractual obligations while the work is delayed?
Different people may provide the answers. The insurer explains its claim decisions and payment records; the mortgage servicer documents its escrow requirements; the contractor addresses price, feasibility, and schedule; technical specialists address their own disciplines. Where those answers conflict, retain both versions and identify the supporting records rather than choosing whichever is more convenient.
Where an independent claim review may help
A public adjuster working within a properly authorized engagement can reconcile the insurer’s estimates, payment history, documented repair scope, and open claim questions. That review may identify an omitted operation, an incomplete payment record, a contractor-side scheduling issue, or an unanswered carrier decision. The result is not always a larger claim; it may be a clearer path to the next action. The distinction between claim adjustment and construction management remains important. A contractor determines the proposed construction means and schedule. Qualified specialists address engineering or environmental concerns. A lender manages its own disbursement process, and counsel evaluates legal questions. Each participant should remain accountable for the decisions within its role.
The bottom line
An issued claim payment is one event in a longer process. A completed restoration requires funds for the authorized work, a supported and executable scope, the necessary approvals, and a contractor able to perform the project. If the home is still unrepaired, identify which of those links is missing and what evidence would allow the next step to proceed. Absolute Adjusting provides public adjusting and defined claim-analysis services, including estimate and payment reconciliation, where authorized and appropriate. The purpose is to make the claim record and unresolved decisions understandable, not to guarantee a settlement, direct construction, or attribute every delay to the insurer.
Sources and further reading
J.D. Power, 2026 U.S. Property Claims Satisfaction Study, March 17, 2026
C&R Magazine, Contractor Connection managed repair survey announcement, October 27, 2026
Insurance Business, Property claims confront a capacity squeeze heading into 2027, October 30, 2026